Wednesday, September 23, 2009

Moody's Might Be In Trouble

I've made mention of ratings agencies being one of the core reasons for the recent housing bubble. Although it's of course too late to help with immediate problems, it is important that we understand what they were doing, why it was bad, and how it can be controlled in the future.

Let me provide some background for the larger context of this post. A commenter and I recently had the following exchange in the comments following a post here:
Wanna said...

Philosophically speaking boom and bust are a way of life and that is the way it should be. Fed should not try to anticipate a boom and nip it in its bud. How would the Fed know in advance that a bubble is going to happen. These things are evident only in hindsight (which of course is 20/20 for TV and market pundits). Fed's job as Greenspan and Bernanke have said before should be that of a mopper rather than a boom-breaker.

Adit said...

Why is it that "boom and bust" is the way it should be? Would it not be better to target steady, sustainable growth rather than extreme run-ups followed by sharp letdowns over and over?

Wanna said...

By suggesting that "Would it not be better to target steady, sustainable growth" you are probably saying that Fed knows two things: 1. the number for steady, sustainable growth. Is it 3% per year, is it 5% per year, is it 8% per year? Which number should Fed use? Depending on which number you pick then the next question is 2. How do you know that is a correct number? China is growing at more than 8% per year. Should Chinese Fed have tried to rein in this party long time back because 8% is such a big number?

This is similar to Monday morning Quarterbacking. Most people's hindsight is perfect.

Mopping up post party is much better than reigning in the party prematurely.


I did not answer in the comment section, but I did put the following hasty thoughts together in an email sent to Wanna later:

I think you make a good point that setting targets is difficult, but at the same time, directly reigning in bubble-like growth isn't necessarily the idea. Instead, I go back to regulatory reform. One example: If there was proper oversight on ratings agencies so that they couldn't rate a big collection of junk as AAA quality when it should have been B or worse, much of the rampant real estate speculation and associated market tools could never have been exploited to the degree they were. This would have indirectly limited the extent of the bubble. Perhaps then, the comments shouldn't be aimed at the Fed, but at the government in general. Basically, I don't see how a bubble like the tech bubble could have been prevented: that was pure speculation that I can't think of reigning in, because it was due to an extremely bullish, forward-looking investment sentiment that was just the market being silly. This more recent bubble might have been less bubble-like if regulations were in place to limit financial "innovation" that really just took advantage of bad gov't. Keep in mind that it also allowed banks to reduce capital requirements which is a more dangerous state of affairs than what existed during the tech bubble. So, you're right: the Fed's job is to clean up after the mess and regulation reform is outside Fed purview. But smart regulation could perhaps mitigate *some* bubbles, which is better than letting them all through. I wonder if the S&L crisis was exploitation of similar gov't inadequacy. Let me predict that your counter will be that there will always be loopholes we will only see in retrospect, and the gov't will thus perpetually be inherently inadequate. I hope this is not true, and I wonder if it comes back again to the lack of financial literacy in the public. If this literacy rate was higher, perhaps financial "innovation" would be more transparent and idiocy would be caught more quickly.


p.s. Wanna's response was indeed that gov't will always be inadequate. I can't dispute that. Not all bubbles can be prevented, not all idiocy can be controlled. However, the government has a responsibility to control what it can. One thing it can control is transparency of ratings given by ratings agencies: it can be argued that these ratings fueled much of the equity market bubble by enabling all the exotic "financial innovations" Wall St. put together during that time. Also, buried in the guest post made yesterday, is a paper from the Dallas Fed arguing against Wanna: it is imperative that we not simply sit back and clean up after the party.

As such, there are two solutions that I see: one, as mentioned in other posts in this blog, is financial literacy. This is a topic that probably goes beyond the scope of this blog, as that seems more like educational policy than anything else. The other is regulatory reform, which I've been hammering at for a while. Congress investigating Moody's is a step in the right direction on that front, though Congress should look at regulation of all various financial institutions and do their best to ensure transparency on all issues. Going after ratings agencies should be one step in a larger, broader process.


Throughout the financial crisis, major credit-ratings firms were criticized for their overly rosy ratings of complex debt securities, which deteriorated soon after and led to billions of dollars of investor losses.

Despite months of regulatory scrutiny and some internal changes at the firms, a recently departed Moody's Corp. analyst says inflated ratings are still being issued. He has taken his concerns to congressional investigators.

The analyst, Eric Kolchinsky, said Moody's Investors Service gave a high rating to a complicated debt security in January 2009 knowing that it was planning to downgrade assets that backed the securities. Within months, the securities were put on review for a downgrade.

"Moody's issued an opinion which was known to be wrong," Mr. Kolchinsky wrote in a July letter to the rating firm's chief compliance officer, a copy of which was reviewed by The Wall Street Journal. In the letter, Mr. Kolchinsky cited other instances in which he believes inflated ratings were given to securities.

Nice Update on SEC (Rakoff) vs. BoA

Last June, when Bank of America CEO Ken Lewis was asked by a U.S. House committee why the bank hadn't disclosed seemingly important information about its upcoming Merrill Lynch acquisition in a proxy statement last November, he had a ready response:

"I'm not a securities lawyer," he said. "I don't decide on disclosures."

...

But now, thanks to U.S. District Judge Jed Rakoff of Manhattan, the stonewall is crumbling.

...

SEC: We can't prove the individual executives did anything wrong because they tell us they simply delegated to their lawyers the task of handling the disclosure obligations.

Rakoff: Then go after the lawyers.

SEC: We don't know what the lawyers said, since the executives invoked their attorney-client privileges.

Rakoff: If the officers are saying they relied on counsel, they're automatically waiving the privilege. Plus, there's a crime-fraud exception to the privilege, so you could have asked me to order them to answer.

SEC: Not really. We haven't charged anybody with fraud. We just charged a lesser infraction -- filing a false proxy statement -- which does not require proof of a fraudulent state-of-mind, so the officers never had to formally invoke a reliance-on-counsel defense. Accordingly, neither the bank nor Merrill ever waived their attorney-client privileges either.

Rakoff: Why didn't you charge anyone with fraud?

SEC: We couldn't prove fraudulent intent.

Rakoff: Why not?

SEC: They said they relied on advice of counsel.

See why Rakoff got steamed?


This article is a great read on the status of the SEC vs. Bank of America case, mostly for that last segment on 'why Rakoff got steamed'. Hopefully, something will come of this. Transparency at the big banks, and on Wall St. in general, is badly needed. This also plays into a post on corporate governance I still need to do.

Tuesday, September 22, 2009

Guest Post on Regulatory Reform and Beyond

I'm excited. Guest post! Always wanted to do this.
FYI - any of you readers, if you want to put some thoughts up here, email me. You all know how to contact me.

This post is from Pramod Khargonekar.


Martin Wolf is a highly respected and influential economist who writes a regular column for Financial Times (www.ft.com). A wonderful article, Call of the Wolf, describing on Martin Wolf can be found at http://www.tnr.com/article/economy/call-the-wolf?page=0,0.

In his article in FT on September 15, 2009 (http://www.ft.com/cms/s/0/b24477de-a226-11de-9caa-00144feabdc0.html), he wrote an excellent piece on what lessons we can take away from the fall of Lehman brothers a year ago.

“If the price of oil stabilises, I believe we can weather the financial crisis at limited cost in terms of real activity.” Thus did Olivier Blanchard, newly appointed head of the International Monetary Fund’s research department, describe the prospects ahead on September 2 2008. He was swiftly proved wrong

Few economists then realised how fragile the global financial system had become. The failure of Lehman Brothers just under two weeks later and the ensuing crisis at AIG, the insurance giant, turned complacency into terror. The financial system plunged into an abyss, dragging the economy behind it.

This is only partially true. People like Roubini, Schiff, and many others did warn of the troubles quite accurately. But the larger point that the collapse stunned most of the people is quite true.

What lessons are we to learn from this shock, a year later?

Above all, the true insurers of the financial system can be seen in our mirrors. According to the IMF’s Global Financial Stability Report of April 2009, total support for the financial system from the governments and central banks of the US, the eurozone and the UK has amounted to $8,955bn (£5,436bn, €6,132bn) – $1,950bn in liquidity support, $2,525n in asset purchases and $4,480bn in guarantees.

These numbers should be etched on a large stone on Wall and Broad Street. To put these numbers in perspective, US annual GDP is around $14,000bn. So, we have spent close to 60% of US annual GDP to support the companies in the financial sector.

These sums are misleadingly precise. The painful truth is that the incomes of taxpayers were put at the disposal of the financial sector’s creditors. When finance ministers and central bank governors of the Group of Seven leading developed countries met in Washington last October, they decided to “take decisive action and use all available tools to support systemically important financial institutions and prevent their failure”. Desperate times; desperate measures.

Since large financial institutions are most likely to fail during a crisis, this amounted to an open-ended government guarantee. What makes the decision quite unbearable is that it was, in my view, also correct. The risk of a cascading failure of the good, the bad and the ugly among financial institutions was apparent. Given what had happened after Lehman’s failure, only fools would have run this experiment. We were not that foolish.


This is the key argument --- the bailout was necessary. There is the other side of the argument which says we should let companies fail. It is impossible to know which would have been the better choice: bailout as was done or let them fail. At this point, it is an academic issue. Indeed, what has been done to deal with this crisis will be used to draw lessons when it comes to future crises which are bound to happen. In this sense, Ben Bernanke, Hank Paulson, Tim Geither, Larry Summers are writing the book which will be studied by future economists and policy makers.

Thus, the lesson learnt from Lehman’s failure was the precise opposite of what many had hoped on the day it was announced: it is that every systemically significant institution must be rescued in a crisis. That lesson is reinforced by Wednesday’s agreement that the rescue, buttressed by unprecedented monetary and fiscal stimulus, has worked: the panic is over and the world economy is on the mend.

We still have so many systemically important institutions. So, there has been no change in the “too big to fail” situation.

Indeed, one can argue that the Lehman failure was necessary. Without such an event, there was no chance of obtaining the resources needed to resolve the crisis, above all from the US Congress. This is what the Harvard historian Niall Ferguson argued in the FT on Tuesday. It is likely that he is right.

Everything, in short, has been for the best in the best of all possible worlds. In retrospect, it was right to let Lehman go, because it caused such a disaster. That then forced a public sector resolution of the crisis and taught that such a failure must never be allowed again. If these are indeed the sorts of lessons we draw, we are making huge mistakes.

We are now getting to the punch lines of the Wolf article:

First, we cannot let stand the doctrine that systemically significant institutions are too big or interconnected to be allowed to fail in a crisis. No normal profit-seeking business can operate without a credible threat of bankruptcy.

Thus, President Barack Obama is correct to call for the “most ambitious overhaul of the financial system since the Great Depression”. The communiqué of the Group of 20 finance ministers and central bank governors outlines the current agenda for reform. It is quite sensible, so far as it goes.

The question, however, remains whether enough will be done to eliminate the present incentives to game the system. It must be possible to wind up institutions without the damage we witnessed after Lehman’s collapse. This has come to be called a “living will”. A better term would be “assisted euthanasia”. Should that be impossible, these institutions must be under the sort of regulation that we normally apply to utilities.


I have previously talked about the “public utility” model for the financial sector. (ed. note: I summarized some of his thoughts on this idea in this post.) It is great to see that Wolf also advocates the same notion. The only other way is to have a well designed system that eliminates the very notion of too big to fail.

The second big potential mistake is to return to the old doctrine that it is better to clean up after a crisis than to take any pre-emptive action. Yet, the more effective the present clean-up seems, the more likely is it that central bankers will draw that lesson. They can argue that, if we have been able to survive such a huge crisis, no changes in the policy orthodoxy are needed.

This would be a huge error, as William White, formerly chief economist of the Bank for International Settlements, argues in a thought-provoking paper.* Mr White, one of the few economists in the official sector to warn of a looming crisis, argues that the “macroprudential” approach, now increasingly accepted, cannot rely on regulation alone. It is almost impossible for such regulation to offset the powerful incentives for credit creation produced by expansionary monetary policies. Thus, argues Mr White, “pre-emptive tightening” should replace “pre-emptive easing”. If we look back at the past two decades of ever more desperate efforts to clean up after crises, the wisdom of this “belt and braces” approach will seem evident.


I think it is an interesting intellectual problem. Can one design a system to detect bubbles? Can one create numerical measures of “bubbliness”? It sounds like an engineering or machine learning problem. It may be hard, possibly impossible, since the system may change over time making the measures designed on the basis of past data inadequate or useless. (ed. note: a commentor on this blog has argued against the idea of preemptive bubble killing in the comments in this post.)

The third big mistake is more immediate: it is to assume that we are already well on the way to a healthy recovery. The financial panic is indeed over, as it should be, given the scale of government guarantees. The economic dangers are not.

The recovery has been fuelled by the bail-out of the financial system and by extraordinary fiscal and monetary policies, particularly in the countries with the highest private-sector leverage. For good reason, the private sectors of such countries are likely to save more and pay down debt for years to come. This, in turn, now necessitates a big swing in the balance between supply and demand in export-dependent economies.

Mr Blanchard has set out the post-crisis macroeconomic agenda in a recent article.** As he puts it, we must manage delicate “rebalancing acts” – first, “rebalancing from public to private spending”; second, “rebalancing aggregate demand across countries”. Unless and until both are managed, the recovery is built on quicksand.


Only the future will tell whether the recovery is sustainable or built on quicksand. It is amazing how the stock market anticipated the current recovery. As it happens, real economy responds to perceptions of people (which in turn are influenced by the stock market and jobs and the real economic conditions. (Soros calls this reflexivity. It is also related to the idea of animal spirits, currently championed by Akerloff and Shiller.)

Letting Lehman go was not our biggest mistake. That was letting the economy and financial system become so vulnerable. Equally, the past year has restored neither the financial system nor the economy to health. We have avoided the worst. That is good. It is not enough.


There it is. A multi trillion dollar question is: will we really make any substantial changes in response to this major collapse which has led to near 10% unemployment rate!

Monday, September 21, 2009

More On Fed-Induced Boom-and-Bust Cycles

The Baseline Scenario adds to the chorus of economists discussing two issues: one, how the Fed has perpetuated the boom-and-bust cycle over the last few decades; two, that serious regulatory reform is needed.
Again, I don't think anything will come of this. However, it's still worth reading and understanding how things work, because if the system remains as is, we're virtually guaranteed to have another great bubble and another great crash. The reason it's worth understanding is because one can at least profit from all this mess by playing the market correctly. Understanding macro cycles is helpful in that regard.

A couple nice paragraphs from the article:
In successive financial boom-busts over the past 30 years, the Fed undertook smaller versions of what Ben Bernanke did over the past 12 months. In the Latin American debt crisis of 1982, the savings-and-loan crisis of the late 1980s, the Asian financial crisis and the collapse of Long-Term Capital Management in 1998 and during the bursting of the dot-com bubble in 2001, you saw the same pattern: First, of course, the financial system grew rapidly, bank profits were large and a bubble emerged. At a certain point, we reached the market peak and stared down the mountain. Bankers frantically called the Fed, and it dutifully stepped in to prevent an economic collapse — by lowering interest rates and providing credit to “maintain liquidity.”
...
In today’s nascent global recovery, we are already seeing bubble-like rises in the prices of real estate and assets, from Hong Kong and Singapore to Brazil. And many more emerging markets will likewise soon boom. The details of who makes which crazy loans to whom will no doubt be different from what they were from 2002 to 2007, but the basic structure of incentives in the system is unchanged. The same people are running the American banks, and the same regulators are regulating them, so you can easily get the same outcome here as we have just seen.

Sunday, September 20, 2009

Weekend Reading

As usual, bold highlighting in quotes is my own emphasis.
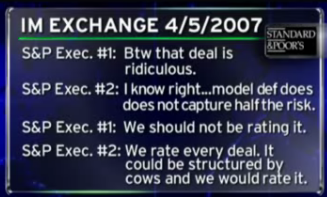
  • Firstly, a great article on Regulatory Arbitrage (which is something all the big banks pulled off during the recent bubble). It was written back in May 09, but it's a great primer for those who want to understand what exactly all those banks were doing with CDO's and why they were created: so that banks did not have to hold much capital. Here's a quick quote to give you a taste: "How does regulatory capital arbitrage work? ... the most straightforward to describe and to implement is securitization. Recall our bank earlier that had $100 in mortgages, for which it had to hold $4 in capital. Let’s say it creates a simple collateralized debt obligation out of these mortgages. It sells them to a special-purpose vehicle (SPV) that issues bonds to investors; these bonds are backed by the cash flows from the monthly mortgage payments. The bonds are divided into a set of tranches ordered by seniority (priority), so the incoming cash flows first pay off the most senior tranche, then the next most senior tranche, and so on. If these are high-quality mortgages, all the credit risk (at least according to the rating agencies) can be concentrated in the bottom few tranches (because it’s unlikely that more than a few percent of borrowers will default), so you end up with a few risky bonds and a lot of “very safe” ones. The magic is that by getting sufficiently high credit ratings for the senior tranches, the bank can lower the risk weights on those assets, thereby lowering the amount of capital it has to hold for those tranches. The risky tranches will require more capital, but it is possible to do the math so that the lower capital requirements on the senior tranches more than outweigh the higher requirements on the junior tranches. So you end up with lower total capital requirements – in some cases, 50% lower – simply through securitization." Thankfully, those ratings agencies are starting to come under fire, an interesting story in and of itself. Look at this ridiculous exchange between two S&P Execs (S&P is one of the big ratings agencies). That old defense of free speech is looking a little less plausible...
  • Janet Yellen, President of the San Francisco Fed, presents her outlook on the economy: "I am hugely relieved that our financial system appears to have survived this near-death experience. And, as painful as this recession has been, I believe that we succeeded in avoiding the second Great Depression that seemed to be a real possibility. Much of the recent economic data suggest that the economy has bottomed out and that the worst risks are behind us. The economy seems to be brushing itself off and beginning its climb out of the deep hole it’s been in. That’s the good news. But I regret to say that I expect the recovery to be tepid. What’s more, the gradual expansion gathering steam will remain vulnerable to shocks. The financial system has improved but is not yet back to normal. It still holds hazards that could derail a fragile recovery. Even if the economy grows as I expect, things won’t feel very good for some time to come. In particular, the unemployment rate will remain elevated for a few more years, meaning hardship for millions of workers. Moreover, the slack in the economy, demonstrated by high unemployment and low utilization of industrial capacity, threatens to push inflation lower at a time when it is already below the level that, in the view of most members of the Federal Open Market Committee (FOMC) best promotes the Fed’s dual mandate for full employment and price stability. As a result, monetary policy makers will continue to face a difficult task in the years ahead."
  • Calculated Risk presenting a couple bullish views on the economy. The author of the post disagrees with those views. (edit: My wording in the previous sentence is ambiguous. "The author" refers to Calculated Risk: the link goes to a CR post that presents two articles with bullish views, and then refutes them. I did not mean to imply I had a personal opinion either way. Sorry for any confusion.) Good points on both sides. Personally, I'm just wondering if the stock market is going to keep going up...
  • Remember the earlier point (4th bullet in my previous post) about how GDP might be overused in measuring the state of a nation? The Economist follows up!
  • More from The Economist, on an interesting new investment playground: patents.
  • Stephen Roach updates his views on the BRIC's. "'It's a myth that the baton of economic leadership is being seamlessly passed to the BRICs, in particular China. My premise is there is still a lot of work to be done,' says Roach." For those who don't know: Stephen Roach is a highly respected analyst and economist for Morgan Stanley, who is now their top executive in Asia. The BRIC's ... well, that's a must read, perhaps the most influential and widely accepted modern paper predicting the changing world landscape. Goldman Sachs' Global Economic Paper No. 99: Dreaming With BRIC's.
  • Peter Schiff revisits the demise of Lehman.
  • Will Flash Trading be banned? Wow, this would be remarkable. I'd prefer to see more efforts at fundamental regulatory reform, but realistically, this is more than I was expecting.
  • Dubuque, Iowa: America's first truly "Smart City"?